DeFi vs Traditional Finance: 12 Essential Differences, Benefits and Hidden Risks Explained
DeFi vs traditional finance compared side by side: how control, cost, access, risk, and regulation differ, and which system fits your money goals best.
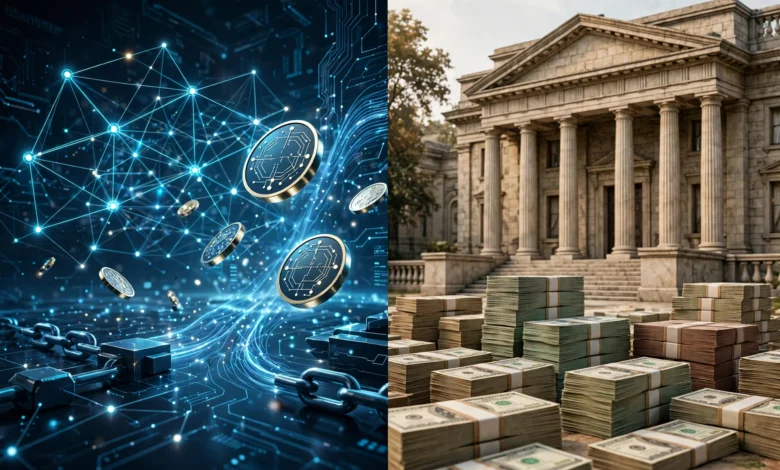
DeFi vs traditional finance is one of the biggest debates in money right now, and it’s no longer just a crypto-insider topic. Banks are experimenting with blockchains, regulators are writing rules for stablecoins, and millions of people now hold savings in apps that have no branch, no opening hours, and no bank manager.
On one side sits traditional finance, often called TradFi: banks, brokers, insurers, and payment networks that have run the global economy for centuries. It’s regulated, familiar, and backed by safety nets like deposit insurance. It’s also slow in places, expensive in others, and out of reach for a large share of the world’s population.
On the other side is decentralized finance, or DeFi: financial services built on public blockchains and run by code instead of companies. You can lend, borrow, trade, and earn interest from a wallet on your phone, any time of day, without asking anyone’s permission. That freedom comes with real trade-offs, including hacks, volatile assets, and very little protection if something goes wrong.
Neither system is simply “better.” They solve different problems and carry different risks. In this guide, we break down 12 key differences between the two, from who controls your money to how fees, speed, transparency, and regulation compare. You’ll also see the main benefits and drawbacks of each, how the two worlds are starting to merge, and how to decide where each one fits in your own financial life.
What Is Traditional Finance?
Traditional finance is the system most of us grew up with. It includes commercial banks, central banks, stock exchanges, brokerages, insurance companies, credit card networks, and the payment rails that move money between them.
The defining feature is centralization. Trusted institutions sit in the middle of almost every transaction. When you send money, your bank debits your account and asks another bank to credit the recipient. When you buy a stock, a broker routes your order, an exchange matches it, and a clearing house settles it. Each step has a company responsible for it, and each company is licensed and supervised by regulators.
How Traditional Finance Works
- Banks take deposits and make loans. They lend out much of what customers deposit and earn the spread between the interest they charge borrowers and what they pay savers.
- Central banks set monetary policy. They influence interest rates and the money supply, and act as lenders of last resort in a crisis.
- Intermediaries handle trust. Banks, brokers, and custodians verify identities, hold assets, and settle trades so strangers can do business safely.
- Regulators oversee the system. Agencies set capital requirements, protect consumers, and enforce rules against fraud and money laundering.
This structure has real strengths. It provides stability, legal recourse, and consumer protections. In many countries, bank deposits are insured up to a set limit by a government-backed program, which is why most people don’t worry about their checking account vanishing overnight.
What Is DeFi (Decentralized Finance)?
Decentralized finance rebuilds financial services on public blockchain networks such as Ethereum, Solana, and their Layer 2 networks. Instead of a bank in the middle, smart contracts handle the work. These are programs that hold funds and execute transactions automatically according to fixed rules anyone can inspect.
For a clear, neutral overview of the building blocks, the Ethereum Foundation’s introduction to DeFi is a good reference.
How DeFi Works
- Self-custody wallets replace bank accounts. You hold your own assets with a private key or seed phrase, rather than trusting a bank to hold them for you.
- Smart contracts replace intermediaries. A lending protocol matches lenders and borrowers automatically. A decentralized exchange swaps tokens using pooled liquidity.
- Stablecoins act as digital dollars. Tokens like USDC are designed to hold a steady value, which makes everyday DeFi use practical.
- Governance is often shared. Many protocols let token holders vote on upgrades and parameters, though in practice influence is often concentrated.
Common DeFi applications include lending and borrowing platforms, decentralized exchanges, stablecoins, yield farming, derivatives, and tokenized real-world assets like government bonds.
DeFi vs Traditional Finance: 12 Key Differences
Here’s where the two systems really part ways. Some differences favor DeFi, some favor TradFi, and several are simply trade-offs that depend on what you value.
1. Who Controls Your Money
In traditional finance, a bank or broker holds your assets on your behalf. That’s convenient, and if you forget your password, you can reset it. But the institution can also freeze your account, block a transfer, or limit withdrawals.
In DeFi, you control your assets directly through a self-custody wallet. Nobody can freeze your funds at the protocol level, though some stablecoin issuers can freeze specific tokens. The flip side is harsh: lose your seed phrase, and your money is gone for good. There’s no reset button.
2. Access and Financial Inclusion
Opening a bank account usually requires identification, a fixed address, and sometimes a minimum balance or credit history. Around the world, many adults still lack access to a formal account.
DeFi is permissionless. Anyone with an internet connection and a wallet can use most protocols. This is one of the strongest arguments for financial inclusion, especially in places with unstable currencies or limited banking. In practice, users still need a way to convert local money into crypto, which often runs through regulated exchanges.
3. Operating Hours and Settlement Speed
Banks and stock markets keep business hours. International wire transfers can take days, and many securities trades still take a business day to settle.
DeFi runs 24/7/365. Transactions settle in seconds or minutes, depending on the blockchain. A loan, a token swap, or a cross-border transfer can be completed on a Sunday night as easily as a Tuesday morning.
4. Transparency
In TradFi, a bank’s books are private. You see your own statements, and regulators see detailed reports, but the public sees only periodic disclosures.
In DeFi, transactions and smart contract code typically sit on a public ledger anyone can inspect. You can verify how much collateral a lending protocol holds in real time. That openness is powerful, though most users lack the skills to read contract code, so they still rely on auditors and analysts.
5. Intermediaries and Costs
Every intermediary in TradFi takes a cut: account fees, wire fees, card fees, brokerage commissions, and currency conversion spreads.
DeFi cuts out many middlemen, which can lower costs, especially for international transfers. But it isn’t free. You pay gas fees to the network, and on busy chains these can spike. Protocol fees and slippage on trades add further costs. On low-fee networks, DeFi transactions can cost fractions of a cent; on congested ones, they can cost more than a bank transfer.
6. Interest Rates and Yields
Bank savings rates are set by institutions and influenced by central bank policy. They tend to be stable and predictable.
DeFi interest rates are set by algorithms based on supply and demand. When borrowing demand rises, rates climb, sometimes sharply. When it falls, so do yields. DeFi can offer higher returns at times, but those returns come with more risk and much less predictability.
7. Lending and Credit
Banks lend based on your identity, income, and credit score. You can get an unsecured loan or a mortgage with relatively little upfront collateral.
Most DeFi lending is overcollateralized. To borrow $1,000, you might need to lock up $1,500 or more in crypto. There’s no credit check, and approval is instant, but if your collateral’s value drops too far, the protocol automatically sells it in a liquidation. That makes DeFi borrowing useful for accessing liquidity without selling assets, but not for people who need credit they can’t already secure.
8. Regulation and Consumer Protection
This is the biggest difference for everyday users. Traditional finance is heavily regulated. Banks must hold capital, follow consumer protection laws, and handle complaints. In many countries, deposits are insured up to a set limit.
DeFi has far fewer safeguards. There’s usually no deposit insurance, no ombudsman, and limited legal recourse if a protocol is hacked or a developer disappears. Regulators are steadily extending rules to stablecoins and crypto service providers, but much of DeFi still operates in a gray area.
9. Security Risks
TradFi faces fraud, data breaches, and occasional bank failures, but institutions carry insurance and are accountable for losses caused by their own failures.
DeFi faces smart contract risk. A coding flaw can let attackers drain funds in minutes, and billions have been lost to exploits over the years. Users also face phishing scams and malicious approvals. Security largely becomes the user’s responsibility.
10. Privacy and Identity
Banks collect detailed personal information under know your customer (KYC) and anti-money laundering rules. Your financial life is private from the public but visible to your bank and the authorities.
DeFi is often described as anonymous, but it’s more accurately pseudonymous. Wallet addresses aren’t tied to names by default, but every transaction is public forever. Once someone links an address to you, your full history is visible.
11. Innovation and Composability
New financial products in TradFi take years of legal work, partnerships, and regulatory approval.
DeFi protocols are composable, often called “money legos.” Developers can plug one protocol into another without asking permission, so new products launch quickly. This speed drives innovation, but it also means risks can stack up and spread fast when one piece fails.
12. Stability and Volatility
Traditional finance deals mainly in government-issued currencies and regulated assets. Prices still move, but bank balances don’t swing 20% in a day.
Much of DeFi runs on volatile crypto assets. Even stablecoins have occasionally lost their peg. If you hold anything other than a well-backed stablecoin, expect large price swings.
DeFi vs Traditional Finance at a Glance
If you want the short version, this table sums up the comparison.
| Feature | Traditional finance (TradFi) | Decentralized finance (DeFi) |
|---|---|---|
| Custody | Bank or broker holds assets | You hold assets in your own wallet |
| Access | ID, address, and approval required | Open to anyone with internet and a wallet |
| Hours | Business hours, holidays closed | 24/7/365 |
| Settlement | Hours to days | Seconds to minutes |
| Transparency | Private books, periodic disclosure | Public ledger, open-source code |
| Costs | Account, wire, and conversion fees | Gas fees, protocol fees, slippage |
| Lending | Credit-based, often unsecured | Overcollateralized, no credit check |
| Interest rates | Set by institutions and central banks | Set by algorithms and market demand |
| Regulation | Heavily regulated | Limited and evolving |
| Deposit insurance | Common, up to set limits | Usually none |
| Main security risk | Fraud, breaches, bank failure | Smart contract bugs, hacks, phishing |
| Privacy | Private but identified (KYC) | Pseudonymous but publicly visible |
| Error recovery | Password resets, disputes, chargebacks | Usually none |
Benefits and Drawbacks of Traditional Finance
Advantages of Traditional Finance
- Consumer protection. Regulations, complaint processes, and courts give you recourse when things go wrong.
- Deposit insurance. Government-backed schemes protect bank deposits up to a limit in many countries.
- Access to credit. You can borrow based on your income and credit history, not just the assets you already own.
- Stability. Balances held in national currencies don’t swing wildly from day to day.
- Ease of use. Forgotten passwords, mistaken transfers, and card fraud can usually be fixed.
Disadvantages of Traditional Finance
- Gatekeeping. Many people are excluded because of paperwork, location, or credit history.
- Higher fees. International transfers and currency conversion can be expensive.
- Slow settlement. Cross-border payments can take days, and markets close on weekends.
- Limited transparency. You can’t see how your bank uses your deposits.
- Control risk. Institutions can freeze accounts or restrict withdrawals, sometimes without much warning.
Benefits and Drawbacks of DeFi
Advantages of DeFi
- Open access. No approvals, minimum balances, or credit checks for most services.
- Full control. You hold your own assets without relying on a third party.
- Speed. Transactions settle quickly and run around the clock.
- Transparency. On-chain data lets anyone verify reserves, loans, and activity in real time.
- Innovation. Composable protocols let new financial tools launch and evolve quickly.
- Global reach. Stablecoins can move value across borders cheaply on low-fee networks.
Disadvantages of DeFi
- Smart contract and hack risk. Bugs and exploits can wipe out funds with no reimbursement.
- No safety net. Deposit insurance and formal complaint channels are generally absent.
- User responsibility. Losing a seed phrase or signing a malicious transaction can mean permanent loss.
- Volatility. Most crypto assets swing sharply, and even stablecoins carry depeg risk.
- Complexity. Wallets, gas fees, approvals, and bridges have a steep learning curve.
- Regulatory uncertainty. Rules are still changing, which can affect access and taxes.
The pattern is clear. Traditional finance trades some freedom and efficiency for protection. DeFi trades protection for freedom, speed, and openness. Which trade-off makes sense depends on what you’re trying to do.
How Regulation Is Shaping DeFi vs Traditional Finance in 2026
For years, the regulatory gap was the clearest line between the two systems. That line is starting to blur, especially around stablecoins, which sit right at the border between crypto and conventional money.
Stablecoin Rules in the United States
The U.S. passed the GENIUS Act, its first federal stablecoin law, in July 2025. It requires payment stablecoins to be backed one-to-one by cash or short-term Treasuries, limits who can issue them, and bars issuers from paying interest directly to holders. Throughout 2026, regulators have been turning the law into detailed rules. The FDIC, for example, approved a proposed rule in April 2026 covering stablecoin issuers it supervises, reserve and redemption standards, and tokenized deposits. You can read the agency’s summary in the FDIC’s notice on GENIUS Act rulemaking. Implementation is still underway ahead of the law’s effective date.
Europe and the Rest of the World
The European Union’s MiCA (Markets in Crypto-Assets) regulation already sets licensing and reserve requirements for crypto service providers and stablecoin issuers. Other major financial centers are building their own frameworks. The general direction is the same: regulate the on-ramps, stablecoins, and custodians, while working out how to treat fully decentralized protocols.
What Regulation Means for DeFi Users
- Stablecoins may become safer and more transparent, with audited reserves and clear redemption rights.
- Front-ends and on-ramps face more compliance, which can mean more identity checks when you move money in or out.
- Pure protocols remain harder to regulate, so many core DeFi risks, like smart contract bugs, stay with the user.
- Tax reporting is tightening in many countries, making it harder to ignore DeFi gains.
Where DeFi and Traditional Finance Are Converging
The old framing of DeFi vs traditional finance as a winner-takes-all fight is fading. Increasingly, the two are borrowing from each other.
Tokenization of Real-World Assets
Large asset managers have launched tokenized funds holding U.S. Treasuries and money market instruments, which can be held and transferred on public blockchains. This tokenization of real-world assets brings traditional investments onto DeFi rails and gives on-chain users access to more stable yields.
Banks Adopting Blockchain Technology
Banks are experimenting with tokenized deposits, stablecoin partnerships, and blockchain-based settlement to speed up payments and cut costs. U.S. banking groups have openly discussed issuing stablecoins, offering crypto custody, or partnering with fintech firms.
Hybrid Finance
Some analysts call this blend hybrid finance or “CeDeFi”: regulated institutions using DeFi-style infrastructure, and DeFi protocols adding compliance features to serve institutional users. For everyday people, this may eventually mean the speed and transparency of blockchains combined with the protections of the banking system.
DeFi or Traditional Finance: Which Is Right for You?
For most people, the honest answer is not either-or. The smarter question is which job each system does best.
When Traditional Finance Makes More Sense
- Your emergency fund and everyday money. Insured, stable, and easy to access when you need it.
- Big life loans. Mortgages, car loans, and student loans rely on credit-based lending DeFi can’t match.
- Retirement and long-term investing. Regulated accounts often come with tax advantages and investor protections.
- When you want someone to call. If mistakes or fraud worry you, institutional support has real value.
When DeFi Can Be Useful
- Cross-border payments. Stablecoins on low-fee networks can move money internationally faster and cheaper than many wire services.
- Access where banking is limited. In places with unstable currencies or few banks, DeFi tools can offer a practical alternative.
- Borrowing against crypto you already hold. You can unlock liquidity without selling, as long as you manage liquidation risk.
- Learning and experimenting. Small, controlled amounts let you understand how open financial systems work.
A Safe Way to Try DeFi
If you’re curious about DeFi but cautious, start with these steps:
- Keep your core savings in traditional finance. Only use money you can afford to lose.
- Set up a reputable self-custody wallet and store your seed phrase offline, never in a screenshot or cloud note.
- Choose a low-fee network so small experiments aren’t eaten up by gas costs.
- Stick to established protocols with long track records and multiple security audits.
- Start with simple actions, like swapping a small amount or supplying a well-known stablecoin to a major lending market.
- Read every transaction before signing, and revoke token approvals you no longer need.
- Keep records of every transaction for tax purposes.
The goal is to understand the differences between DeFi and traditional finance from experience, without betting your financial security on it. This article is for general education and isn’t financial or legal advice.
Conclusion
The debate over DeFi vs traditional finance comes down to a basic trade-off between protection and freedom. Traditional finance keeps your money inside a regulated system of banks, brokers, and insurers that offers deposit insurance, credit-based lending, stable balances, and someone to call when things go wrong, at the cost of fees, slower settlement, limited hours, and gatekeeping that leaves many people out. Decentralized finance replaces those intermediaries with smart contracts and self-custody wallets, giving anyone with an internet connection open, transparent, round-the-clock access to lending, trading, and payments, but it shifts nearly all the risk onto the user through hacks, volatile assets, overcollateralized loans, and the absence of safety nets. Regulation like the GENIUS Act and MiCA, along with tokenized assets and bank experiments with blockchain, is pulling the two worlds closer together. For most people, the sensible path is to keep essential savings and major borrowing in traditional finance, treat DeFi as a tool for specific jobs like cross-border payments or learning, and only commit money they can afford to lose.